Think rallies that double in a day are about good news?
They’re often pure mechanics.
When traders borrow shares to short (sell now, buy back later), rising prices turn that bet into a timed bill: brokers issue margin calls and force cover buys.
That forced buying floods a thin market, eats available asks, and creates a feedback loop that pushes price sharply higher.
This post breaks down the chain reaction, what triggers it, the key metrics that signal danger, and how options and low float can turn a squeeze into a 20 to 100 percent intraday move.
Core Mechanics Behind Rapid Momentum in Short Squeezes
A short squeeze starts when short sellers borrow shares and sell them at current prices, betting the stock drops. Each short position is basically a promise: the borrower has to buy those shares back and return them. When the stock goes up instead of down, those borrowed shares turn into a liability that’s ticking louder every minute. Rising prices trigger margin calls. Brokers demand more collateral or force shorts to close right now. This forced buying floods the market with buy orders exactly when sellers are scarce, creating a feedback loop that keeps pushing prices higher.
The chain reaction is mechanical. And brutal. A trader shorts 1,000 shares at $20, expecting it to hit $15. Then the stock jumps to $30. At $40, the loss crosses 100 percent of the initial position value, forcing a margin call. When hundreds or thousands of short sellers face identical pressure at the same time, their collective covering demand overwhelms whatever shares are actually available. Each forced buyback pushes the next ask price higher. Each new high triggers the next wave of stops and margin calls, compounding the upward pressure in minutes or hours.
This cascade is why short squeezes produce some of the fastest momentum moves in equity markets. Volume surges as covering orders stack up. Long traders see the spike and read it as a breakout, adding speculative demand on top of the mechanical buying from shorts. The result? Price trajectories that can climb 20, 50, even 100 percent in a single session before reversing just as fast when covering demand runs dry.
Key mechanics that amplify momentum during a short squeeze:
High short interest creates a large pool of future buy orders already locked into the market.
Shrinking float reduces available shares, making each covering purchase more impactful on price.
Rising volume confirms active covering and attracts momentum traders who add fuel.
Rapid price acceleration compounds margin pressure and triggers additional stop orders from shorts.
Margin call cascade forces simultaneous exits, eliminating the natural stagger that would dampen price moves.
Market Conditions That Increase Short Squeeze Momentum Potential
Short squeezes need specific conditions to generate rapid momentum. The most critical metric? Short interest as a percentage of float. When 20, 30, or even 50 percent of a stock’s available shares are sold short, the supply of shares available for shorts to repurchase gets severely constrained. Each percentage point of float shorted represents locked future demand that can be triggered by the right catalyst. Days to cover, calculated by dividing total short interest by average daily trading volume, tells you how many sessions it would take for shorts to exit at normal volume. A days to cover value above three signals enough concentrated short exposure to drive sustained covering pressure if a rally begins.
Borrow costs and float tightness amplify squeeze potential even more. When a stock becomes “hard to borrow,” brokers charge elevated fees, often 10, 20, or even 100 percent annualized. Rising borrow fees indicate supply is dwindling and warn that covering could turn forced rather than voluntary. Stocks with low public float, where insiders or institutions hold most shares, concentrate short positions into a smaller trading pool. That concentration means any surge in buying demand meets limited resistance. Ask prices rise faster.
| Metric | What It Indicates | Why It Matters |
|---|---|---|
| Short Interest % | Percentage of float sold short | High percentages (>20%) create large pools of forced future buying |
| Days to Cover | Short interest ÷ average daily volume | Values above 3 mean covering takes multiple sessions and compounds pressure |
| Borrow Fee Rate | Annualized cost to borrow shares | Elevated fees (>10%) signal tight supply and rising exit urgency |
| Float Tightness | Public float as % of shares outstanding | Low float concentrates short exposure and reduces available supply for covering |
Price Action and Order Flow Dynamics During Short Squeezes
When a short squeeze ignites, the order book undergoes a structural shift that amplifies price momentum far beyond typical volatility. Market makers and liquidity providers rely on balanced two sided flow, continuously quoting bids and asks around fair value. A surge of covering demand disrupts that balance by consuming all nearby ask orders, forcing the next round of executions to trade at progressively higher prices. Because prices are discovered by matching incoming orders to the best available quotes, a sudden wave of market buy orders from panicked shorts lifts the entire ask ladder. Each execution clears one ask level and exposes the next, often at a significantly higher price. That’s what creates the vertical price spikes visible on intraday charts.
Bid ask spreads widen dramatically as liquidity providers recognize the imbalance and pull back limit orders. In normal conditions, a stock might trade with a one or two cent spread. During a squeeze, spreads can balloon to 50 cents, a dollar, or more as dealers demand greater compensation for being on the wrong side of a momentum surge. This widening makes executions less predictable and more costly, especially for traders trying to exit quickly. The combination of rising prices and widening spreads traps late entrants who chase the move, often executing near temporary peaks just before the first pullback.
Volume spikes serve as the most reliable signal that covering, not simple speculation, is driving the move. Sustained high volume indicates continuous forced buying as shorts work through their obligations over multiple time intervals. A single candle volume burst without follow through often reflects speculative interest that fades quickly. True short covering produces waves of volume over minutes, hours, or even days. Each wave represents a new cohort of shorts hitting margin thresholds and exiting. When volume dries up after a parabolic climb, it signals covering demand has been exhausted and momentum is vulnerable to sharp reversal.
Options Activity and Gamma Dynamics That Accelerate Short Squeezes
Heavy options activity, particularly in out of the money calls, introduces a second layer of mechanical buying that can turn a standard short squeeze into a multi day parabolic event. When retail traders or speculators pile into weekly or monthly call options, market makers who sell those contracts must hedge their exposure by purchasing shares. This hedging process is driven by delta (the rate of change of option value relative to stock price) and gamma (the rate of change of delta). As the stock rises and approaches the strike prices of those calls, delta increases and market makers are forced to buy more shares to remain hedged. That mechanical buying adds to the upward pressure already created by short covering, compounding momentum in both directions.
How Gamma Exposure Forces Market Makers to Buy
Market makers dynamically adjust their hedge ratios as stock prices move. A call option that starts deep out of the money with a delta of 0.10 may climb to a delta of 0.50 or higher as the stock rallies toward the strike. For every 1,000 calls sold, a market maker might need to buy 50,000 additional shares to maintain a neutral position. When thousands of contracts cluster at nearby strikes, the aggregate hedging demand can rival or exceed the forced buying from short covering itself. This gamma driven buying is purely mechanical, not based on fundamental views. It creates upward pressure that persists as long as the stock remains near high gamma strike zones.
Call Buying Surges and Upward Price Feedback
Retail interest in short dated call options often surges once a squeeze begins, as traders chase momentum and speculate on further gains. Each new round of call buying forces market makers to purchase more shares, which pushes the stock higher, which increases the delta of existing calls, which requires additional hedging. This feedback loop can produce extreme intraday moves where price climbs in sharp, stair step bursts each time a new strike level is breached. The effect is most pronounced in low float stocks where the total share count available for hedging is small. Weekly options expiration cycles frequently align with the peak intensity of gamma driven rallies, as time decay accelerates and hedging adjustments become more volatile.
Implied Volatility and Options Signal Shifts
Implied volatility in options prices reflects the market’s expectation of future price swings. During the early stages of a short squeeze, IV often spikes as demand for both calls and puts increases. A rapid climb in IV, particularly if the skew tilts heavily toward calls, signals that speculative positioning is building and that market makers are pricing in outsized risk. Elevated IV also raises the cost of new option purchases, which can slow the feedback loop once premiums become prohibitively expensive. Monitoring IV changes in real time provides an early signal of whether gamma dynamics are likely to persist or fade.
Indicators of an emerging gamma squeeze:
Unusually high open interest in near term, out of the money call options.
Rapid increases in implied volatility, especially in call contracts.
Price action that accelerates in steps as the stock crosses popular strike prices.
Volume surges that coincide with options expiration dates or intraday pin risk near key strikes.
Historical High Momentum Short Squeezes: GameStop, AMC, Volkswagen
GameStop in January 2021 remains the most publicized example of a retail driven short squeeze amplified by social media coordination. The stock traded around $17 at the start of January and surged to an intraday high near $483 on January 28, closing that session above $300. Short interest exceeded 100 percent of the float at points during the run, meaning more shares were sold short than were available for public trading. Coordinated buying on Reddit’s WallStreetBets forum, combined with heavy call option demand, triggered both short covering and gamma driven hedging from market makers. Hedge funds holding large short positions reported multi billion dollar losses as forced covering intensified throughout the month. The stock’s subsequent volatility, with daily swings of 20 to 50 percent, illustrated the explosive momentum and rapid reversals characteristic of extreme squeezes.
AMC Entertainment experienced a similar dynamic in mid 2021, with the stock climbing from single digits in early 2021 to an intraday peak above $72 on June 2, 2021. Short interest remained elevated throughout the rally, and retail traders used the same social media playbook that had worked with GameStop. The squeeze unfolded over several weeks rather than a single dramatic spike, with multiple waves of momentum as shorts attempted to re enter and were forced to cover again during subsequent rallies. AMC’s float was larger than GameStop’s, which moderated the peak percentage gains but still produced multi hundred percent returns for early participants. The episodic nature of AMC’s squeeze showed that momentum can persist in cycles rather than resolving in a single parabolic move.
Volkswagen’s 2008 short squeeze remains the fastest and most extreme example in modern market history. On October 28, 2008, Porsche disclosed that it controlled 74 percent of Volkswagen’s shares through direct holdings and cash settled options, leaving only about 6 percent of shares in public circulation. Hedge funds and institutional investors who had shorted Volkswagen, expecting the stock to decline during the global financial crisis, faced an immediate supply crisis. The stock doubled in a single day, briefly making Volkswagen the world’s most valuable company by market cap. The squeeze resolved within days as Porsche agreed to lend shares to facilitate covering, but the event demonstrated how a sudden revelation about float scarcity can trigger instantaneous, violent momentum.
Key data from major historical squeezes:
GameStop (Jan 2021): Rose from around $17 to intraday high of $483. Short interest exceeded float. Driven by retail coordination, options activity, and forced hedge fund covering.
AMC (June 2021): Climbed from around $10 to intraday peak of $72. Multi week episodic squeeze with repeated covering waves. Large retail participation via social platforms.
Volkswagen (Oct 2008): Doubled in one session after Porsche disclosure. Float reduced to around 6% of shares outstanding. Resolved in days but briefly made VW the world’s largest company by market cap.
Indicators and Early Warning Signals for Detecting a Potential Short Squeeze
Identifying a stock with squeeze potential before momentum accelerates requires monitoring a combination of quantitative metrics and qualitative sentiment shifts. The first screen is days to cover, calculated by dividing total short interest by average daily trading volume. A value above three days signals that shorts would need multiple sessions to exit at normal volume levels, increasing the likelihood that covering will drive sustained upward pressure. Pairing days to cover with short interest as a percentage of float gives a clearer picture. If 30 percent of the float is short and days to cover is five, any catalyst that sparks buying can quickly overwhelm available supply.
Borrow availability and cost provide real time signals of tightening conditions. Brokers publish lists of hard to borrow stocks and adjust borrow fees dynamically. When a stock moves from “easy to borrow” to “hard to borrow” or when fees spike from 5 percent to 20 percent annualized, it indicates that lendable inventory is shrinking and shorts are facing higher costs to maintain positions. Rising borrow costs add urgency to exit decisions and make it more expensive for new shorts to enter, compressing the supply side further. Options data, particularly unusual surges in call open interest or implied volatility, can signal that speculative interest is building and that market makers may soon need to hedge by buying shares.
Key measurable indicators for detecting squeeze setups early:
Days to cover above 3: Covering will take multiple sessions and compounds upward pressure.
Short interest >20% of float: High percentage creates large locked future buying demand.
Rising borrow fees: Fees above 10% annualized signal tight supply and increasing urgency to exit.
Volume breakouts: Sudden multi day volume increases confirm that covering or speculative buying has started.
Moving average crossovers: Price breaking above 20 or 50 day moving averages often triggers technical buy signals and stops.
Unusual options activity: Spikes in call open interest or IV skew suggest positioning that can trigger gamma hedging.
Risks of Trading Short Squeezes and Why Momentum Often Fades Fast
Short squeezes produce some of the fastest gains in equity markets, but the same mechanics that drive parabolic rallies also create extreme downside risk and rapid reversals. Volatility spikes during squeezes aren’t symmetrical. Intraday price swings of 20, 30, or 50 percent become routine. The speed of those moves makes traditional risk management techniques less effective. Stop loss orders that would protect capital in normal conditions often execute at prices far worse than intended as spreads widen and liquidity evaporates. Traders entering late in the move, driven by FOMO, frequently buy near temporary peaks just before the first sharp pullback. Potential gains turn into immediate losses.
Margin amplification is particularly dangerous during squeezes. Leverage that seems manageable in stable markets becomes lethal when prices move 10 or 20 percent in minutes. A 2:1 leveraged position can be wiped out by a 50 percent adverse move. Brokers will liquidate positions without warning once maintenance margin thresholds are breached. For short sellers, the risk is theoretically unlimited because there’s no cap on how high a stock can rise. Even traders on the long side face execution risk, as widening bid ask spreads and disappearing liquidity make it difficult to exit positions at any reasonable price during peak volatility.
Empirical data on day trading profitability underscores the low probability of consistent success in high volatility environments like short squeezes. A 2014 study analyzing 3.7 billion trades from 1992 to 2006 found that only 9.81 percent of day trading volume was generated by predictably profitable traders. These traders represented less than 3 percent of all active day traders on an average day. A separate study covering 1,146 brokerage accounts from March through June 2000 found that 50 percent were profitable, with an average net profit of $16,619, but that profitability wasn’t consistent across time periods. Another study of 334 accounts from February 1998 to October 1999 found that only 35 percent were profitable, and just 14 percent generated profits exceeding $10,000. Short squeeze trading offers explosive potential returns but carries outsized risk and very low odds of repeatable success for most participants.
| Risk | Effect on Traders |
|---|---|
| Extreme Volatility | Intraday swings of 20% to 50% make stop loss orders unreliable and turn profitable positions into losses within minutes |
| Widening Spreads | Bid ask spreads expand from pennies to dollars, causing executions far from quoted prices and trapping exits |
| Margin Calls and Forced Liquidation | Leverage amplifies losses and brokers liquidate positions automatically, often at the worst possible prices during peak volatility |
Trading Strategies to Navigate and Benefit From Momentum in Short Squeezes
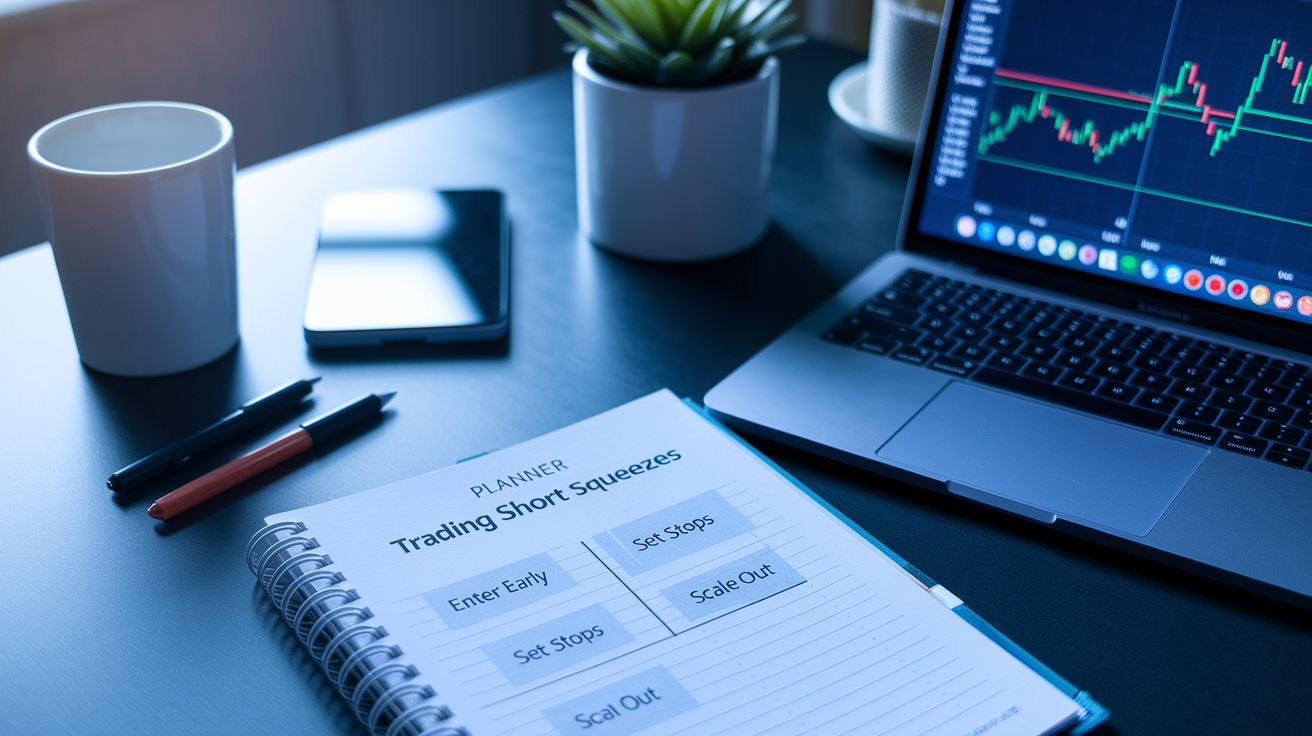
Successful navigation of short squeeze momentum requires entering early, defining exits before the trade, and managing position size to survive the inevitable volatility. The highest probability setups occur when short interest and days to cover are elevated, a clear catalyst emerges, and volume begins to confirm that covering has started. Entering on the initial breakout, ideally with volume surging above the 20 day average, positions a trader ahead of the forced covering wave rather than chasing it. Late entries, especially after the stock has already doubled or tripled, carry the highest risk because momentum can reverse as abruptly as it started once covering demand is exhausted.
Core principles for trading short squeeze momentum:
Enter early on catalyst confirmation: Identify high short interest and a clear trigger (earnings, news, technical breakout) before the parabolic phase begins.
Set predefined stop loss and profit targets: Decide exit levels in advance and execute them mechanically, not emotionally, as price swings accelerate.
Scale out to lock in gains: Take partial profits at predetermined levels (50%, 100% gains) and reduce position size as the move extends to manage risk.
Avoid using margin or leverage: Squeeze volatility can trigger forced liquidations. Trade only with capital you can afford to lose entirely.
Monitor volume to confirm covering persistence: Sustained high volume indicates ongoing forced buying. Volume drop offs signal exhaustion and reversal risk.
Tactical Entry Timing
The optimal entry point is the initial breakout above a prior resistance level or moving average, confirmed by a volume surge at least 200 to 300 percent of the recent daily average. This breakout often coincides with the first wave of short covering and precedes the parabolic phase. Waiting for a pullback after the initial spike can work if volume remains elevated and the stock holds above the breakout level, but many squeezes don’t provide clean pullbacks before accelerating further. Use limit orders rather than market orders to control entry price, especially in fast moving, wide spread environments.
Conservative Exit and Risk Controls
Scaling out of positions as price rises allows you to lock in profits while retaining exposure to further upside. A common approach is to sell one third of the position at a 50 percent gain, another third at 100 percent, and hold the final third with a trailing stop to capture extended moves. Stop loss placement is critical. Set stops below recent intraday lows or key moving averages, but recognize that volatile squeezes can trigger stops and reverse quickly. For added protection, consider using options to hedge. Buying a put option on a long stock position caps downside risk if the squeeze reverses violently, though the cost of elevated implied volatility during squeezes makes this hedge expensive. The key is to decide all exit rules before entering the trade, because once momentum accelerates, emotional decision making replaces discipline and leads to poor outcomes.
Final Words
Shares can spike hard when forced buyers rush in, rising prices trigger margin calls, shorts scramble to cover, and liquidity evaporates. This piece ran through the chain: mechanics, market setup, order-flow, gamma effects, case studies, warning signs, risks, and trading rules.
Watch high short interest, tight float, volume surges, and heavy call buying. Those signals can turn a small move into a parabolic run, and then a fast unwind.
Understanding how short squeezes create rapid stock momentum helps you spot setups, size smarter, and plan exits. Use the checklist here, trade with rules, and stay prepared.
FAQ
Q: Does a short squeeze make a stock go up?
A: A short squeeze makes a stock go up by forcing short sellers to buy shares to cover, adding urgent buying pressure that can push prices sharply higher, often for a short period.
Q: What is the 3 5 7 rule in stocks?
A: The 3-5-7 rule in stocks is an informal trade-management guideline: take partial profits or tighten stops at roughly 3%, 5%, and 7% price moves to lock gains and limit risk.
Q: What are the 10 most shorted stocks?
A: The 10 most shorted stocks change constantly; check short-interest data from exchange filings, FINRA, or services like Fintel, S3, or your broker to get the current top-10 list.
Q: What is the mother of all short squeezes?
A: The “mother of all short squeezes” usually refers to Volkswagen in 2008, when Porsche’s stake disclosure triggered frantic short covering and a brief price spike that vaulted VW’s market value.